
High-Volume Compliance Platforms: What to Evaluate
What breaks a compliance platform at high alert volume: queue age, rule noise, analyst minutes, and audit reconstruction.
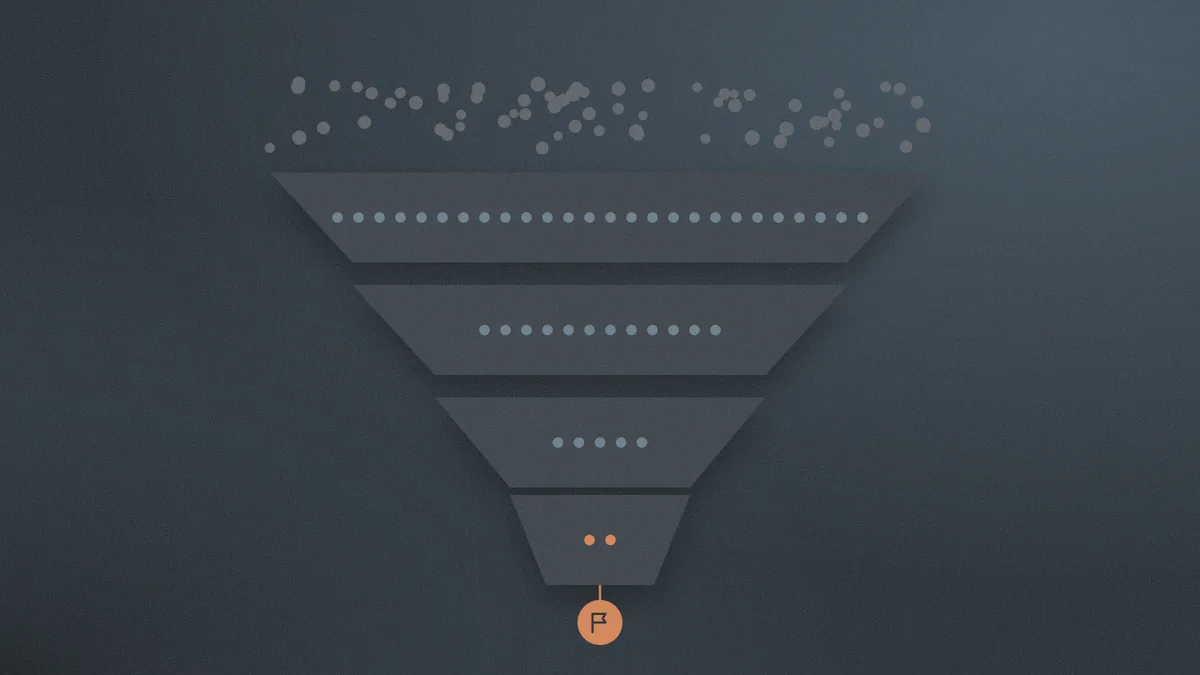
What breaks a compliance platform at high alert volume: queue age, rule noise, analyst minutes, and audit reconstruction.
Manual KYB cost covers analyst time, rework, lost onboardings, missed owners, and later audit reconstruction. Corporate reviews average $2,274.
KYC false positives start in the name match. FCA tests found 75% detection on slight variants. How list scope and date of birth clear the rest.
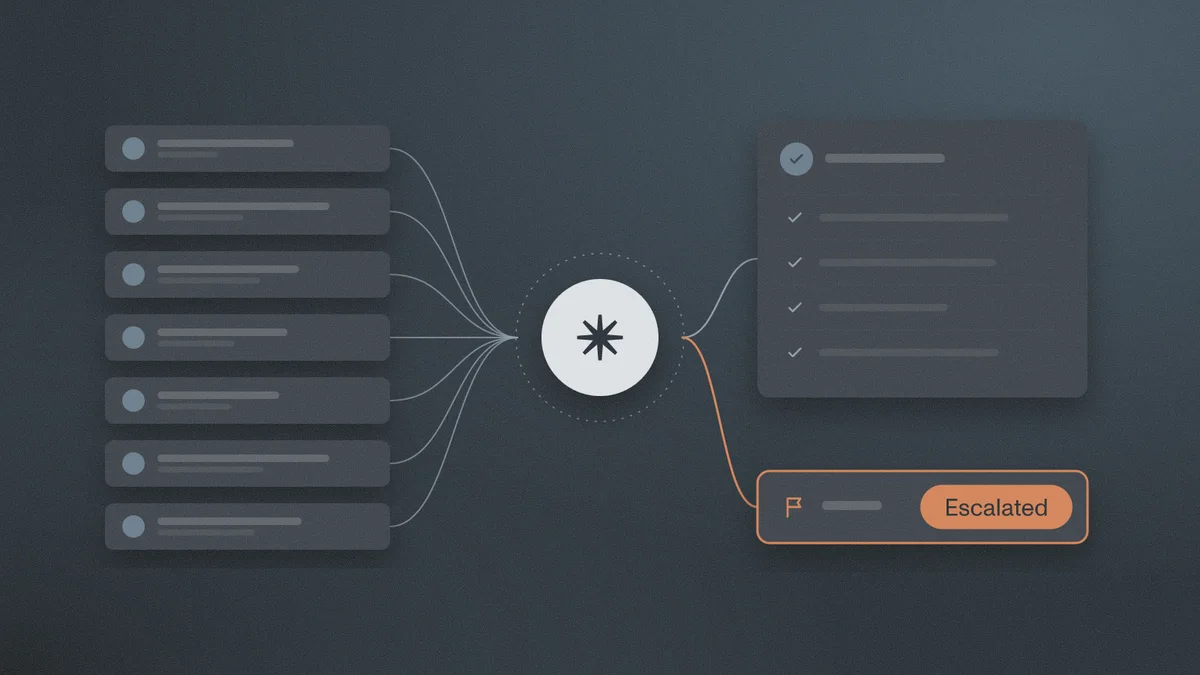
How to backtest AML rules on historical data, run shadow mode and champion-challenger in production, and document results for model risk management.
How entity resolution and graph analytics identify beneficial owners: probabilistic matching, blocking, indirect ownership math, cycles, registry limits.
Brazil's betting ban pushes 30M bettors to illegal sites. What Pix monitoring teams will see, SPA Ordinance 2,750's red flags, and why alert queues flood.
What the crypto Travel Rule requires of VASPs: FATF R.16, FinCEN's $3,000 rule, EU and UK thresholds, self-hosted wallets, IVMS 101, and the sunrise gap.
How bust-out fraud works, how it differs from default and account takeover, the signals and features that catch it, and why the loss ends up as a SAR.
How fuzzy name matching works in sanctions screening: Levenshtein, Jaro-Winkler, phonetic keys, OFAC's own scorer, threshold trade-offs, and validation.
Wire fraud detection for banks: known-number callbacks, beneficiary checks, mule holds, and 24-hour IC3 recall. IC3 reported $20.877B in 2025 losses.
BSA independent testing: independence, risk-based frequency, sampling, board reporting, and what OCC examiners expect after Bulletin 2025-37.
How banks evaluate AML vendors under OCC and FFIEC third-party risk rules, including residual BSA risk for processors, screening, BPO, and model vendors.
What the GENIUS Act requires of stablecoin issuers: reserves, BSA program, seize and freeze capability, Travel Rule, MiCA comparison, and the secondary market gap.
Credit unions face document fraud at three unique entry points: member onboarding, indirect lending, and shared branching. How to evaluate detection at credit union scale.
Financial crime detection identifies suspicious activity after the fact. Prevention stops it before funds move. Here is how to evaluate the right balance for your compliance program.
What banks must verify, monitor, and document under FinCEN's CDD Rule — including the 2026 beneficial ownership changes and how to evaluate your program.
Modern fraud detection layers ML scoring, behavioral biometrics, and graph neural networks to catch fraud in milliseconds while reducing false positives.
Sphinx's real-time AML monitoring evaluates transactions before settlement using agentic AI, replacing batch processing for instant payment rails like FedNow.
Ranked comparison of the best fraud detection platforms in 2026 covering Feedzai, NICE Actimize, Featurespace, SAS, and Hawk AI with an evaluation framework.
UBO identification traces beneficial ownership through corporate layers to find the natural persons who own or control an entity.
Claude Fable 5 was banned three days after launch, then reinstated. Here's what the episode means for compliance teams adopting AI.
Try another keyword or explore a different topic.